Flood Damage Compensation in Turkey: Will Insurance Pay?
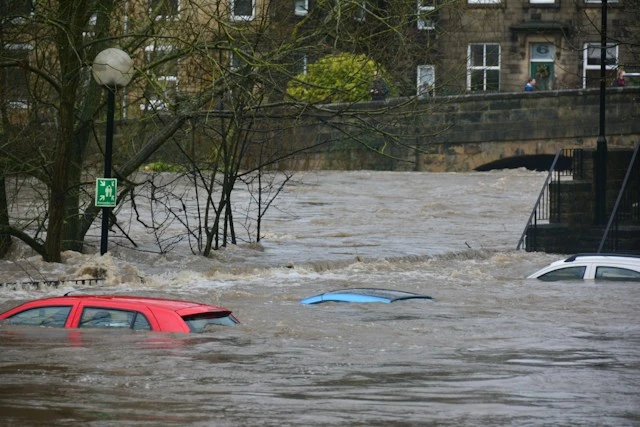
If your home, car or business has been damaged by flooding, you may be wondering: Who will pay for the damage, and how can you claim compensation?
The answer depends on the cause of the damage and the terms of your insurance policy. Some rules are clear: standard DASK earthquake insurance does not cover flooding unrelated to an earthquake. Comprehensive motor insurance does not automatically cover flood damage unless the relevant coverage is included in the policy. Home and business insurance policies must also be checked for specific flood protection.
If your insurer refuses to pay or offers less than the amount of your loss, you may have options to challenge the decision. If you have no insurance, a compensation claim against a potentially responsible person or public authority may also be worth investigating.
IMPORTANT!
Do not rely solely on photographs and a notification to your insurer. Document the cause of the damage, the amount of your loss and the deadlines that apply to your claim. Missing a statutory deadline, particularly in claims against public authorities, can seriously affect your legal rights
Who Pays for Flood Damage in Turkey?
The answer depends on how the damage occurred.
Cause or circumstances
Where to start
Flood damage covered by home insurance
Your home insurance company
Covered flood damage to business premises
Your business insurance company
Vehicle damage covered by comprehensive motor insurance
Your motor insurer
Damage allegedly caused by deficient public infrastructure
The relevant public authority
Damage caused by another person or private company
The potentially responsible person or company, and any applicable liability insurer
These options are not always mutually exclusive. Receiving insurance compensation does not necessarily prevent an investigation into whether another person or public authority was also responsible. However, you cannot recover compensation twice for the same loss, and the insurer may have a right of recourse after making payment.
Does DASK Cover Flood Damage?
No. Standard DASK coverage does not cover flooding unrelated to an earthquake. DASK is Turkey’s Compulsory Earthquake Insurance scheme. Within the applicable policy limits, it covers specified building damage directly caused by earthquakes and certain related risks, including fire, explosion, tsunami and landslide resulting from an earthquake.
Flooding is not included in the standard coverage simply because a property is insured under DASK.
Does Home or Business Insurance Cover Flood Damage?
If your policy includes flood and inundation coverage, you may claim compensation for damage that falls within the insured risks and satisfies the policy conditions. Without that coverage, flood damage is not automatically covered merely because you have fire insurance.
Article A.3.2 of the Turkish Fire Insurance General Conditions identifies flood and inundation as risks that may be included through an additional contractual arrangement.
Check the following points in your policy:
Building or contents: Coverage for the building does not necessarily mean that all household belongings are also insured.
Flood or internal water damage: Floodwater entering from outside may be treated differently from damage caused by a burst internal water pipe.
Limits and deductibles: Your policy may impose a maximum payment or require you to bear part of the loss.
Warning!Businesses may also suffer lost income when flooding forces them to suspend operations. However, business interruption and loss-of-profits claims are not automatically covered unless the policy includes the relevant protection.
Does Comprehensive Car Insurance Cover Flood Damage?
If your comprehensive motor insurance policy includes flood and inundation coverage, you may claim compensation for vehicle damage covered by the policy. Having comprehensive insurance alone is not sufficient if that protection is excluded.
Floodwater can damage the engine, electronic components, electrical systems and interior of a vehicle.
If your vehicle has been exposed to floodwater, do not attempt to start the engine. Photograph and record the vehicle’s condition, then notify your insurer and arrange the required inspection.
Does compulsory motor third-party liability insurance cover flood damage to my own vehicle?
No, not as a general rule. Compulsory motor third-party liability insurance primarily covers qualifying damage caused to third parties in connection with the use of the insured vehicle. It is not designed to cover flood damage to the insured vehicle itself.
What Should I Do If the Insurance Company Refuses to Pay?
If your insurer rejects your claim or pays less than you believe you are entitled to, take the following steps.
Step 1: Request the reason in writing. Ask the insurer to explain why it rejected the claim or calculated a lower payment, and identify the policy provisions on which it relies.
Step 2: Gather evidence. Keep photographs, videos, invoices, repair estimates, expert reports and service records. Identify each damage item that you believe has been omitted or undervalued.
Step 3: Submit a written objection. Explain your claim and provide the supporting documents. Keep proof that your application reached the insurer.
Step 4: Consider further legal action. If the dispute is not resolved, you may be able to apply to the Insurance Arbitration Commission or the competent court, provided the applicable requirements are met.
How long does an insurance company have to pay?
Article 1427 of the Turkish Commercial Code regulates when insurance compensation becomes due. As a general rule, the required documents must be submitted and the investigation completed. The law also provides a 45-day period following notification of the insured event, subject to statutory conditions and exceptions.
If the investigation cannot be completed within three months, the law provides for an advance payment of at least 50% of the assessed loss under the applicable conditions, based on the preliminary expert assessment.
These provisions do not mean that every claim must automatically be paid regardless of missing documents or statutory exceptions.
When Can I Apply to the Insurance Arbitration Commission?
Before applying to the Insurance Arbitration Commission, you must first submit a written claim to the insurance company.
According to the Commission’s official guidance, you may be eligible to apply if the insurer issues an unsatisfactory final response or fails to respond within the applicable period. The general response period is 15 business days; for compulsory motor third-party liability insurance, it is 15 days.
Other eligibility requirements must also be satisfied.
Can I Claim Compensation from a Municipality if I Have No Insurance?
Yes, compensation may be available if the legal requirements for public authority liability are satisfied. However, the fact that flooding occurred does not automatically make a municipality liable.
For example, the damage may be connected to inadequate stormwater drainage, problems with sewerage infrastructure or a failure to carry out necessary maintenance within the relevant authority’s area of responsibility.
Frequently Asked Questions
Can I claim compensation if I do not have receipts for damaged belongings?
Yes. Photographs, bank records, warranty documents and other evidence may help establish the existence and value of the damaged items.
Can I discard damaged belongings before the insurance expert visits?
Where possible, document the damage and allow an inspection first. If urgent action is necessary, take photographs and videos before removing the items.
I am a tenant. Who can I claim compensation from?
Damage to the building and damage to your personal belongings may be treated differently. The responsibilities of the landlord, insurers and other potentially liable parties depend on the circumstances.
Can I recover hotel costs if my home becomes uninhabitable?
You may be able to claim these costs if your policy covers temporary accommodation. Otherwise, a claim against another party requires a legal basis and evidence of the expenses.
What if the expert's report understates my losses?
Submit a written objection identifying the disputed items and support it with photographs, invoices, repair estimates or a technical assessment.
Can I still claim compensation if I have already repaired the damage?
Repairing the property does not automatically eliminate your right to compensation. However, document the damage as thoroughly as possible and retain repair invoices and other evidence.
Flood damage in Turkey? Learn about home and car insurance, rejected claims, compensation deadlines and claims against responsible public authorities...
How do you file a name change lawsuit? We’ve explained the valid grounds, the competent court, the required documents, the 2026 fees, and the name change process for those living abroad...
Requirements for permanently importing vehicles into Turkey for those living abroad who plan to return permanently to Turkey, the 24-month rule, customs procedures, and taxes...
How can you obtain Turkish citizenship by residing in Turkey for 5 years without interruption? Updated requirements for 2026, required documents, types of residence permits, rules regarding...
Planning to bring your pet to Turkey? Learn the requirements including microchip rules, rabies vaccination, titer test, airline regulations and procedures...
The "closed neighborhood" rule for foreigners in Istanbul has been lifted as of June 10, 2026. Learn about the new residence permit application process here...
Can you bring unlimited gold or cash by paying tax? Avoid costly mistakes—learn the 2026 customs limits and commercial entry rules before you travel...
What Are the Intellectual Property Rights of Software Developers and Clients? Key Considerations Regarding Software Copyright and Employment Contracts...
An amnesty has been introduced in Turkey for illegal foreigners who want to work in domestic services. As of March 2025, Ministry of Interior will allow individuals who cannot schedule an appointment...